 877.227.4484
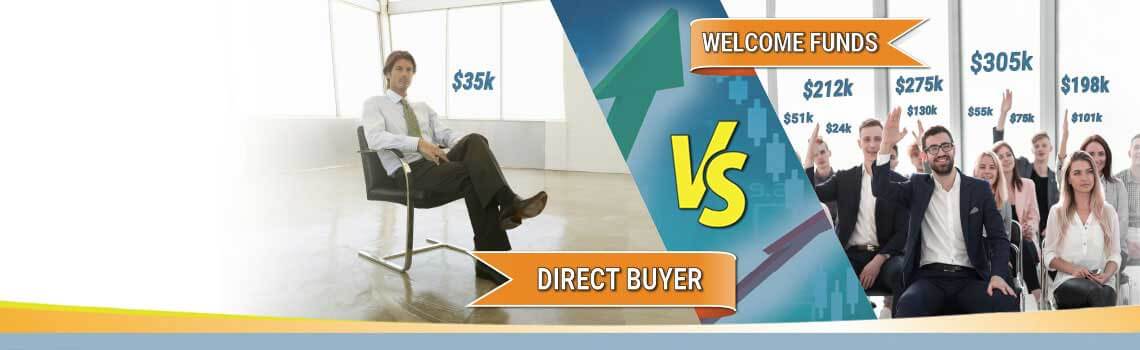
Life Settlement Broker vs. Direct Buyer: Key Differences
A life settlement broker represents the policy owner and markets the policy to multiple state-licensed buyers to solicit competing bids. A direct buyer — a licensed life settlement provider — purchases policies for its own account and represents its own interests in the transaction. Both paths are regulated and both can be legitimate. The right choice depends on how much competition, representation, and price discovery you want before selling an asset you can only sell once.
Two different roles in the same market
The secondary market for life insurance has two kinds of licensed participants a policy owner may deal with. A life settlement provider is a buyer: it acquires policies for its own account or on behalf of investors, and it is entitled to pursue its own economic interests in a purchase. A life settlement broker is an intermediary who represents the policy owner’s interests: its job is to present the policy to multiple providers, solicit bids, and negotiate on the owner’s behalf.
Neither role is inherently better or worse — most states license and regulate both. But they are structurally different, and knowing which one you are talking to is the first question to settle before sharing any information.
Market access: one offer versus competing bids
When you sell directly to a provider, you receive that provider’s offer. It may be a fair offer — but by definition it was not tested against competing bids, and you have no independent way to know what other buyers would have paid.
When you sell through a broker, the policy is presented to multiple licensed providers, each aware that it is competing. That competition is designed to improve price discovery: buyers who want the policy must consider what rivals might bid. Competition does not guarantee a higher price in every case, but it replaces a single data point with a market test.
Compensation and disclosure
Brokers are compensated for their work, typically through a commission paid out of the transaction, and most states require that compensation to be disclosed to the policy owner in writing. Direct buyers do not charge a commission — but the absence of a commission does not by itself mean the owner nets more, because there are also no competing bids pushing the price upward.
The useful comparison is not "commission versus no commission." It is net proceeds to you: the amount you would keep from the best offer obtained through competition, after disclosed compensation, versus the amount a single buyer offers directly. Ask for both numbers in writing before deciding.
Conflicts to understand on both sides
- A direct buyer’s incentive. A provider’s economic interest is to acquire the policy at the lowest price consistent with winning the transaction. That is not misconduct — it is simply what buyers do — but it means a direct offer is a negotiating position, not an appraisal.
- A broker’s incentive. A broker’s compensation is typically tied to the transaction, which generally aligns the broker with a higher price — but you should still ask any broker exactly how its compensation is calculated and when it is disclosed.
- Hybrid and affiliated arrangements. Some companies operate under multiple licenses or have affiliations with buyers. Ask directly whether the company, or any affiliate, could end up owning your policy.
Side-by-side comparison
| Consideration | Life Settlement Broker | Direct Buyer |
| Who they represent | The policy owner’s interests | Its own account and investors |
| Number of potential offers | Multiple — the policy is shopped to competing licensed buyers | One — that buyer’s own offer |
| How the price is set | Competitive bidding among providers | The buyer’s internal pricing |
| Compensation | Commission, disclosed in writing as required by state law | No commission; profits from trading or a mark up fee to the investor |
| Negotiation on your behalf | Yes — negotiating bids upward is the broker’s role | No — you negotiate for yourself |
| Speed and simplicity | A marketed process takes longer than a single offer | Can be faster; one counterparty |
| May suit owners who | Want the price tested by market competition before selling | Have an offer they consider acceptable and value speed over price testing |
Licensing note: both brokers and providers are regulated under state insurance law in most states, and licensing varies by state. Your state insurance department can confirm whether a specific company is licensed to act in your state.
Questions to ask any life settlement company
Whichever route you consider, put these questions to the company in writing and keep the answers:
- Are you licensed to act in my state, and under which license — broker or provider?
- Do you represent me in this transaction, or are you (or an affiliate) the buyer?
- How many licensed buyers will see my policy, and can I see every offer received?
- How are you compensated, how is it calculated, and will it be disclosed to me in writing before I accept an offer?
- Who will see my medical records, and how are they protected before and after they leave your office?
- What happens if I decline every offer — do I owe anything?
- How are settlement funds protected at closing (for example, through an independent escrow arrangement)?
- What conditions or contingencies attach to any offer, and what could change the amount between acceptance and closing?
- Can my financial advisor, attorney, or family member be involved at every step?
Where Welcome Funds fits
Welcome Funds, Inc. is a viatical and life settlement broker. In states where it is licensed or otherwise authorized to act, it represents the policy owner’s interests and markets qualifying policies to state-licensed providers through its competitive auction process. Welcome Funds does not purchase policies for its own account, so it is never on the other side of the table from its clients.
If you already hold a direct offer, a broker review is a low-risk way to test it: the existing offer effectively becomes the floor, and the auction shows whether the market will beat it.
Frequently asked questions
Is it cheaper to sell directly, since there is no broker commission?
Not necessarily. What matters is the amount you keep, and a single uncontested offer may be lower than the net result of a competitive process even after disclosed compensation. The only reliable way to compare is to see both figures in writing before you commit.
I already have an offer from a direct buyer. Can I still use a broker?
Generally yes, if you have not signed a binding agreement. An existing offer can serve as a baseline while a broker tests the market for competing bids. Review anything you have signed — some documents include exclusivity periods — before engaging anyone else.
Are brokers and direct buyers both regulated?
In most states, yes — state insurance law governs both roles, with licensing, disclosure, and consumer-protection requirements that vary by state. Your state insurance department can confirm a company’s license status and standing.
How do I verify a company’s license?
Contact your state insurance department or check its online license lookup, and ask the company for its license number in your state. A legitimate broker or provider will provide it without hesitation.
Will a broker show me every offer, or just the best one?
Ask — and get the answer in writing. Welcome Funds’ practice is to present offers to the policy owner so the decision is made with the full picture of bids and counter-bids. Any company you work with should be willing to make the same commitment.
Test the market before you accept any offer
Whether you are starting from zero or already holding a direct offer, a competitive review shows you what the market will actually pay — before you sign anything.
Call 877.227.4484 · or request a no-obligation policy review online
LIFE SETTLEMENT BLOG
Direct Life Settlement Buyers vs. Welcome Funds – Advisor Beware!
Posted: by John Welcom
Welcome Funds has the privilege of working with numerous financial advisors and wealth managers – and have done so for two decades – some who exclusively focus on servicing high net worth clients. One such advisor who is active in the life settlement market — and already understands the value he can create for his clients — had historically negotiated directly himself with two or three leading buyers of life insurance policies. He thought that simply engaging with mor...
How to Sell Your Life Insurance Policy for $4,743,000 Instead of $275,485?
Posted: by John Welcom
Mr. Williams purchased $10 Million in life insurance coverage in 2001 to provide his family with financial security. Over time, his financial priorities changed: his wife passed away, his children became financially independent, financial burdens arose and the estate tax exemption increased substantially.
Suitability of Life Settlements
Posted: by John Welcom
Traditionally, estate planning advisors counsel their high net worth clients to obtain life insurance policies with large death benefits. The strategy is simple: create a vehicle for heirs to receive tax-free income at the time of an insured’s passing so sufficient funds are available to pay large estate tax bills when assets are inherited.
What is the Most Suitable Exit Strategy for Life Insurance?
Posted: by John Welcom
All eyes in the life insurance agency and the financial advisory world have been on New York, where in the summer of 2019, the New York State Supreme Court paved the way for implementation of Insurance Regulation 187. This rule imposes a new standard for agents and brokers when issuing a recommendation to a client regarding an annuity or life insurance product.
How to Get the Highest Life Settlement Offer
Posted: by John Welcom
When you decide to sell a valuable personal asset, you usually want to obtain the highest purchase price for that property. It is sound business sense. However, how do you truly know when you have reached the point of accepting and securing the most desirable offer?
Understanding the Fair Market Value of a Life Insurance Policy
Posted: by John Welcom
When a professional advisor identifies a life insurance policy that a client no longer needs or wishes to maintain, he should ask, as standard protocol, whether that policy may have value in the secondary market. If so, the client may be able to sell the policy in a life settlement transaction, enabling him to receive a higher cash payout than he otherwise would obtain by lapsing or surrendering the policy back to the insurance company.
The Power of a Life Settlement Auction
Posted: by John Welcom
Professional advisors with clients who no longer need or wish to maintain a life insurance policy have options when exploring the secondary market. Many advisors prudently rely on a licensed life settlement broker to assist them in the sale of the policy and with all aspects of the transaction. However, there is still a large number of professionals persuaded to work directly with only one buyer, called a life settlement provider.
Rebuttals to the “Direct Buyer” Model for Life Settlements
Posted: by John Welcom
Most professional advisors who explore the potential sale of an unwanted life insurance policy on behalf of their clients will rely on the assistance of a licensed life settlement broker. Life settlement brokers represent the policy owner in the transaction and have a duty to act in their best interests. Most notably, the broker’s and client’s goal is aligned: to sell the policy for the highest price possible.
Carrier Resistance To Life Settlements: Clients Need To Know They Can Sell Their Policies
Posted: by John Welcom
Consumers who sell their life insurance policies in the life settlement market receive as much as seven times more money than they would have received by surrendering their policies back to the insurance companies. Seven times! However, an estimated 9 out of 10 policies are allowed to lapse before paying a claim, according to the Life Insurance...
The Danger of Trying to “Time the Market” for Life Settlements
Posted: by John Welcom
Most investors in the stock market understand the danger of “market timing” — trying to choose the right day to buy a stock when the price is low and sell it when the price is high.